
Can You Get Business Loans Without a Bank Account?
Yes! Obtaining capital to invest in your business is absolutely possible, even if you don’t have legal immigration status or a valid SSN.
Why do lenders require a bank account?
It can be challenging to get a loan if you don’t have a savings or a checking account. Lenders typically require it to verify your identity and income. However, some lenders will work with borrowers who don’t have a bank account.
How to Get a Loan Without a Bank Account:
Use Your ITIN. You can still get a loan without a Social Security Number if you don’t have a bank account. One option is to use your Individual Taxpayer Identification Number (ITIN).
Some financial institutions will allow you to use your ITIN instead of an SSN when applying for a business loan.
While not all financial institutions will accept an ITIN in place of a Social Security Number for a business loan—significantly larger financial institutions—community banks, smaller banks, and local credit unions might approve you.
So, in a way, the answer to “How to get a loan without a Social Security Number?” is an ITIN.

What is an ITIN?
An ITIN (or Individual Taxpayer Identification Number) is a tax processing number.
The IRS (Internal Revenue Service) issues this nine-digit number to individuals who are not eligible to obtain a valid SSN but who the law requires to file an individual income tax return.
Obtaining an ITIN will not change your immigration status but will allow you to apply for loans to finance your business.
It is an obligation for every individual in the U.S. to file taxes, regardless of their immigration status. Even undocumented immigrants must file taxes by law if they are working and earning an income in the U.S.
How to Get an ITIN
Getting an ITIN is a pretty straightforward process. To obtain one, you must:
- Fill out form W-7, available in English and Spanish.
- Present a document that proves your identity, such as a passport or driver’s license.
- You must also attach a complete federal tax return. This means the IRS process your ITIN and your tax return simultaneously.
- Send your application by mail, or take it to an IRS office or to a qualified agent for processing.
- In about six weeks, you will receive a letter from the IRS with your ITIN number.
The Benefit of Getting an Individual Taxpayer Identification Number
ITINs initially served the sole purpose of allowing non-U.S. residents to file federal taxes.
Still, they are slowly transitioning into being an alternative to a Social Security Number for immigrants who are hoping to access capital for their business.
More financial institutions and non-profit lenders are expanding their offerings to accept an ITIN in place of an SSN.
Keep in mind that an ITIN does not change your legal status; it only serves as a replacement for an SSN in some instances if you cannot get one.
Loan Options if You Don’t Have a Bank Account
After getting your ITIN, you will need to look for a lender who offers financing with this document.
There are plenty of options for applying for a loan without a bank account: from a private lender, a payday loan, or a peer-to-peer lending platform.
We’ve listed the financing options to help you find the right for your needs; then, you will have to seek a lender to accept you with an ITIN and with the loan product you need.
Source: https://www.caminofinancial.com/

Are you ready to take the next step to buy your home and start building a legacy for your family?…Let me help you!
I am a Brazilian Licensed Realtor at Re-Connect, LLC with 17+ years of experience in the Real Estate industry. I speaks 3 languages (Portuguese, English, Spanish)
CALL NOW: (617) 201-9188 Ana Roque |209 West Central Street, Natick, MA


Is Buying a Two-Family Home in Massachusetts a Smart Investment? Discover the benefits, rental income potential, financing options, hidden costs, and important considerations before investing in a two-family property in Massachusetts. Buying a two-family home in Massachusetts can be an excellent opportunity for homebuyers who Read more
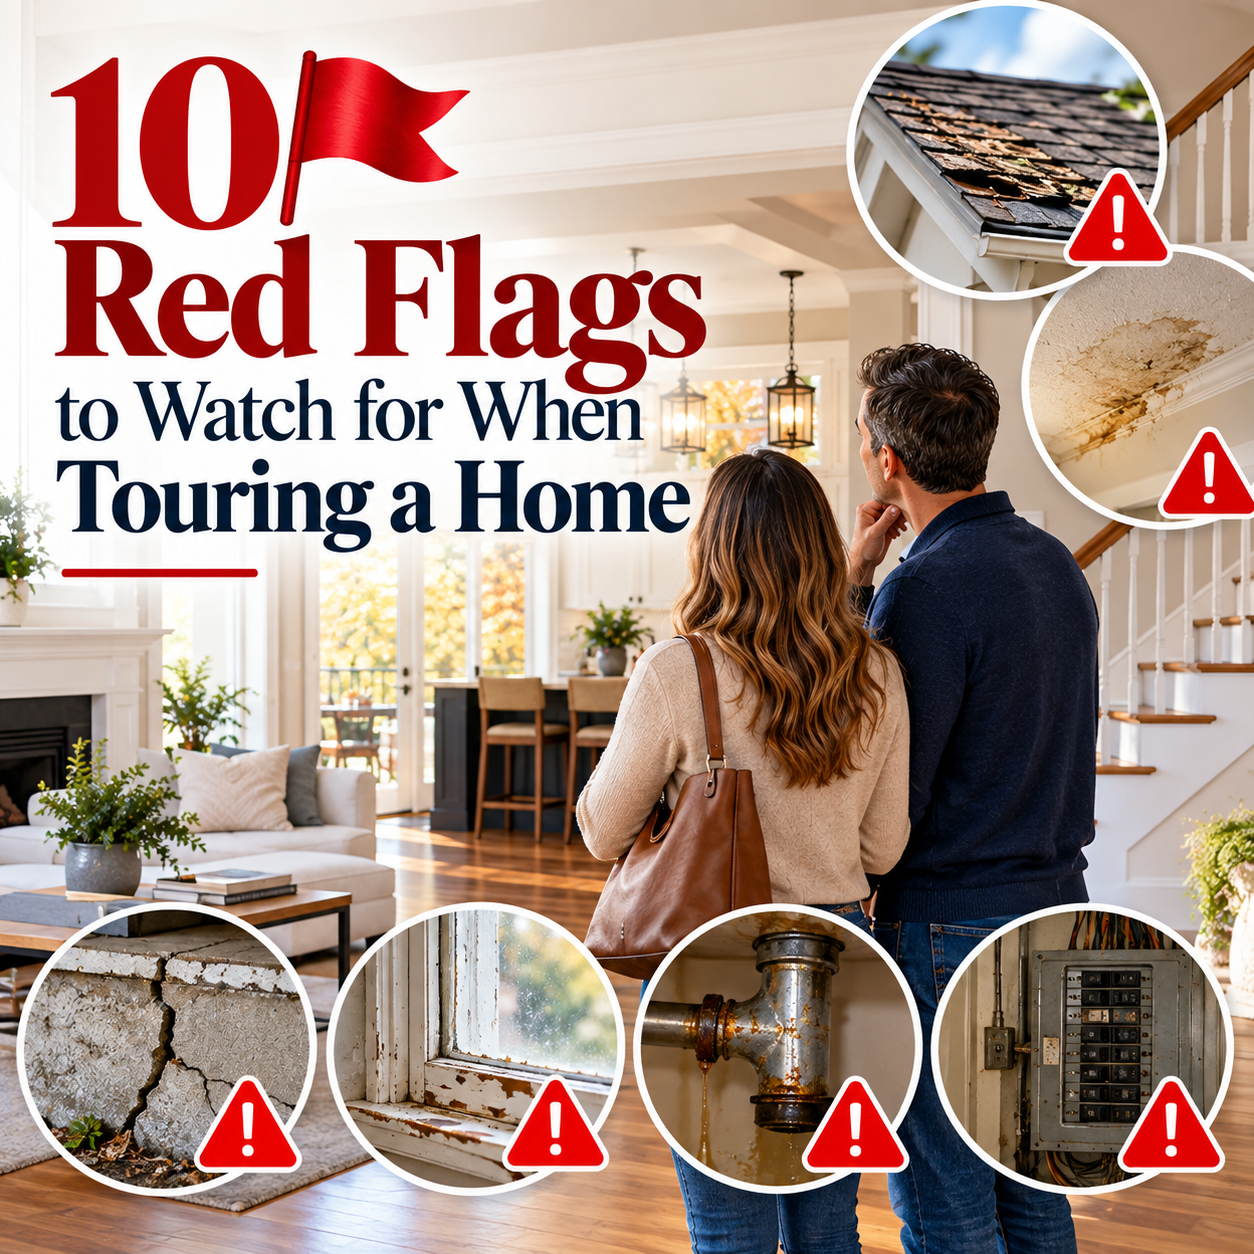
10 Red Flags to Watch for When Touring a Home Touring homes can be one of the most exciting parts of the home-buying process. It's easy to imagine where your furniture will go, picture yourself cooking in the kitchen, or fall in love with a Read more
Massachusetts First-Time Home Buyer Programs to Know About Reading Time: 6–7 minutes the down payment, closing costs, mortgage payments, and competitive home prices. However, first-time buyers may have access to several programs designed to make homeownership more affordable. From down payment assistance to affordable mortgage Read more
Should You Buy a Condo, Townhouse, or Single-Family Home in Massachusetts? When searching for a home in Massachusetts, choosing the right location and price range is only part of the decision. You also need to decide what type of property best fits your lifestyle, budget, Read more