How Much Money Do You Really Need to Buy a Home in Massachusetts?
Buying a home is one of the biggest financial decisions most people will ever make. If you’re planning to buy a home in Massachusetts in 2026, one of your first questions is probably: How much money do I actually need?
The answer involves much more than the down payment. Buyers should also prepare for closing costs, inspections, prepaid expenses, moving costs, and money for unexpected repairs after receiving the keys.
The good news is that you do not necessarily need a 20% down payment to become a homeowner. Depending on your mortgage program, financial situation, and eligibility, you may be able to purchase a home with considerably less.
Let’s break down the major expenses you should consider when preparing to buy a Massachusetts home.
💰 1. Your Down Payment
The down payment is usually the largest upfront expense when purchasing a home.
Although 20% is often mentioned as the traditional down payment, many buyers purchase homes with less. The amount required depends on the type of mortgage and your qualifications.
Some conventional mortgage programs may allow qualified borrowers to put down as little as 3%, while FHA loans can permit down payments starting at 3.5% for borrowers who meet applicable requirements. Certain eligible borrowers may also qualify for VA or USDA financing with no down payment.
For example, on a $500,000 home, a 3% down payment would be $15,000, while 10% would be $50,000 and 20% would be $100,000.
Keep in mind that putting less than 20% down may result in additional mortgage insurance costs, depending on the loan program.
📑 2. Don’t Forget About Closing Costs
Your down payment isn’t the only money you’ll need at closing.
Closing costs include various fees and expenses associated with completing the purchase and obtaining your mortgage.
These may include:
📄 Lender and loan-related fees
⚖️ Attorney or legal expenses
🏠 Appraisal costs
🔎 Title-related expenses
🛡️ Homeowners insurance
💵 Prepaid property taxes and escrow deposits
📋 Recording and other transaction fees
The exact amount varies considerably based on the property, lender, loan, municipality, insurance, and transaction.
Instead of relying on a single percentage estimate, ask your lender for a detailed Loan Estimate early in the mortgage process so you can understand your expected cash requirements.
🔎 3. Budget for the Home Inspection
A home inspection is another expense buyers should consider when creating their budget.
An inspection can help identify potential problems with the property, including issues involving the roof, electrical system, plumbing, foundation, heating and cooling systems, moisture, and other components.
Older Massachusetts homes may deserve particular attention because some properties have systems or building materials that have been in place for decades.
Depending on the property, buyers might also consider specialized inspections or testing for issues such as radon, pests, septic systems, wells, or environmental concerns.
Think of inspections as part of your overall home-buying budget rather than an unexpected last-minute expense.
🏦 4. Earnest Money and Deposits
Massachusetts real estate transactions can involve deposits at different stages of the purchase process.
When making an offer, a buyer may provide an initial deposit. Additional funds may be due when the Purchase and Sale Agreement is signed, depending on the terms of the transaction.
These deposits are generally credited toward the amount you owe at closing rather than being an additional purchase cost.
However, buyers need to understand when the money is due and under what circumstances deposits may be refundable or at risk.
Your real estate agent and attorney can explain the specific terms of your transaction before you sign agreements or transfer funds.
🏠 5. Property Taxes and Homeowners Insurance
Owning a home comes with expenses that continue long after closing.
Massachusetts property taxes vary significantly from one municipality to another. Two similarly priced homes in different towns can have very different annual property tax bills.
You will also typically need homeowners insurance. Your mortgage lender may require proof of coverage before the loan can close.
When comparing properties, don’t look only at the monthly principal and interest payment. Consider your estimated total monthly housing expense, which may include mortgage principal, interest, property taxes, homeowners insurance, mortgage insurance, and HOA or condominium fees when applicable.
🔧 6. Keep Money Available for Repairs and Maintenance
One mistake buyers can make is spending nearly all their available cash on the purchase itself.
After closing, the home becomes your responsibility.
A water heater can fail. An appliance may need replacement. The heating system may require service. A roof can eventually need repairs. Even a move-in-ready home will require routine maintenance.
For this reason, maintaining an emergency fund after closing can be just as important as saving enough money to purchase the property.
Your ideal reserve will depend on the home’s age and condition, your monthly expenses, and your personal financial situation.
🚚 7. Moving and Immediate Home Expenses
Don’t overlook the smaller expenses that quickly add up after purchasing a house.
You may need money for movers, utility setup, furniture, window coverings, locks, basic tools, landscaping equipment, paint, minor repairs, or other necessities.
If you’re moving from an apartment into a single-family home, you may suddenly become responsible for maintenance tasks that were previously handled by a landlord.
Planning for these expenses before closing can make the transition into homeownership much easier.
🎯 So, How Much Cash Should You Have?
There isn’t one number that works for every Massachusetts home buyer.
Suppose you’re considering a $500,000 home. A simplified example might look like this:
3% down payment: $15,000
5% down payment: $25,000
10% down payment: $50,000
20% down payment: $100,000
But the down payment is only the beginning.
You also need to consider closing costs, inspections, prepaid expenses, moving costs, and the amount of savings you want to keep available after closing.
That’s why the question shouldn’t simply be:
“How much do I need for the down payment?”
A better question is:
“How much cash do I need to comfortably purchase the home and still have financial reserves afterward?”
🌟 First-Time Home Buyer Assistance May Help
If you’re a first-time home buyer in Massachusetts, don’t automatically assume you need to save the entire amount on your own.
Massachusetts offers homeownership programs, and eligible buyers may have access to mortgage products or down payment assistance.
Eligibility can depend on factors such as income, location, property type, purchase price, household circumstances, and the specific program.
Because programs and requirements can change, buyers should verify current options with participating lenders and official Massachusetts housing resources before making financial decisions.
📊 Get Pre-Approved Before You Start Shopping
One of the best early steps is to speak with a mortgage professional and obtain a mortgage pre-approval.
Pre-approval can help you understand how much you may be able to borrow, what type of mortgage may fit your situation, what your estimated monthly payment could be, and approximately how much cash you may need to complete the purchase.
Remember that being approved for a certain loan amount doesn’t necessarily mean you should spend the maximum amount available.
Choose a housing budget that also leaves room for your other expenses, savings goals, and lifestyle.
🔑 Work With a Massachusetts Realtor
Understanding the financial side of buying a home can feel complicated, especially for a first-time buyer.
A knowledgeable Massachusetts Realtor can help you understand local home prices, identify properties within your budget, coordinate with your lender and attorney, prepare an offer, negotiate transaction terms, and guide you through the process from your initial home search to closing.
🏡 Preparation Is the Key to Successful Homeownership
You don’t necessarily need 20% down to buy a home in Massachusetts, but you do need a realistic financial plan.
Your savings should account for more than the down payment. Consider closing costs, inspections, insurance, taxes, moving expenses, maintenance, and emergency reserves when determining whether you’re financially prepared.
The more you understand your true costs before you begin shopping, the better prepared you’ll be to make informed decisions when the right home comes along.
Is Fall 2026 a Good Time to Buy a Home in Massachusetts? Fall can be an excellent time to buy a home in Massachusetts. While spring and summer traditionally attract more buyers, the autumn market often creates opportunities for people who are prepared to move Read more
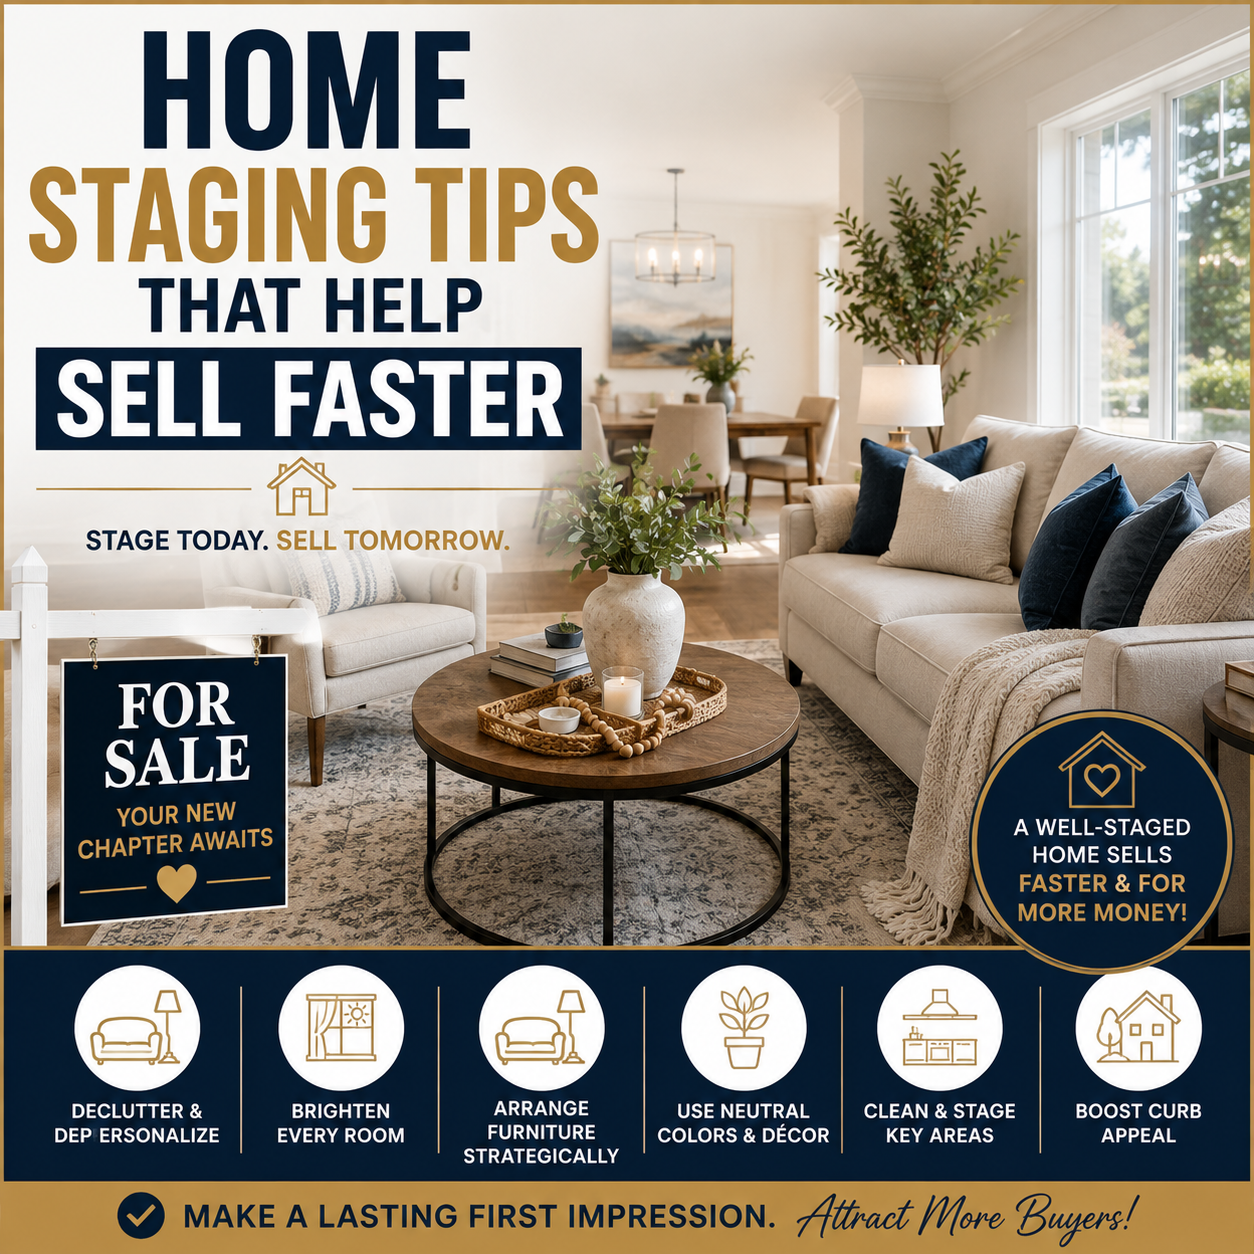
Home Staging Tips That Help Sell Faster When you're preparing to sell your home, first impressions matter. Buyers often decide how they feel about a property within the first few minutes of a showing—and sometimes before they ever walk through the door. That's where home Read more
How to Price Your Home Correctly in Massachusetts Selling your home in Massachusetts begins with one of the most important decisions you'll make: choosing the right listing price. Price too high, and qualified buyers may overlook your property. Price too low, and you could potentially Read more
Should You Renovate Before Selling Your House? Selling a home often raises an important question: Should you renovate before putting your house on the market? For Massachusetts homeowners, the answer depends on the property's current condition, the local real estate market, your budget, and the Read more